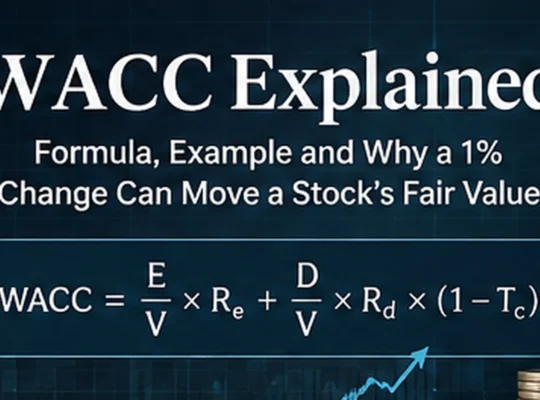
Research basis: September 2026. Market capitalization is one of the first numbers investors learn. Enterprise value is usually one of the first numbers they misunderstand.
That is understandable because market cap feels tangible. Take the share price, multiply it by diluted shares outstanding, and you have the market value of the common equity. Enterprise value asks a different question: what is the approximate value of the operating business to all capital providers, not only common shareholders?
The distinction matters whenever debt, cash, preferred stock, leases or minority interests are large enough to change the economics. Two companies can have identical market caps and radically different enterprise values. One may have a fortress balance sheet. The other may carry debt equal to half its equity value.
This guide explains enterprise value from first principles, shows why EV and market cap answer different questions, and demonstrates how to use the metric without turning it into another mechanical valuation shortcut.
What is enterprise value?
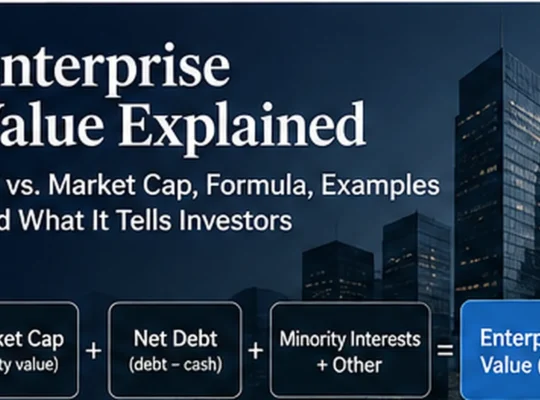
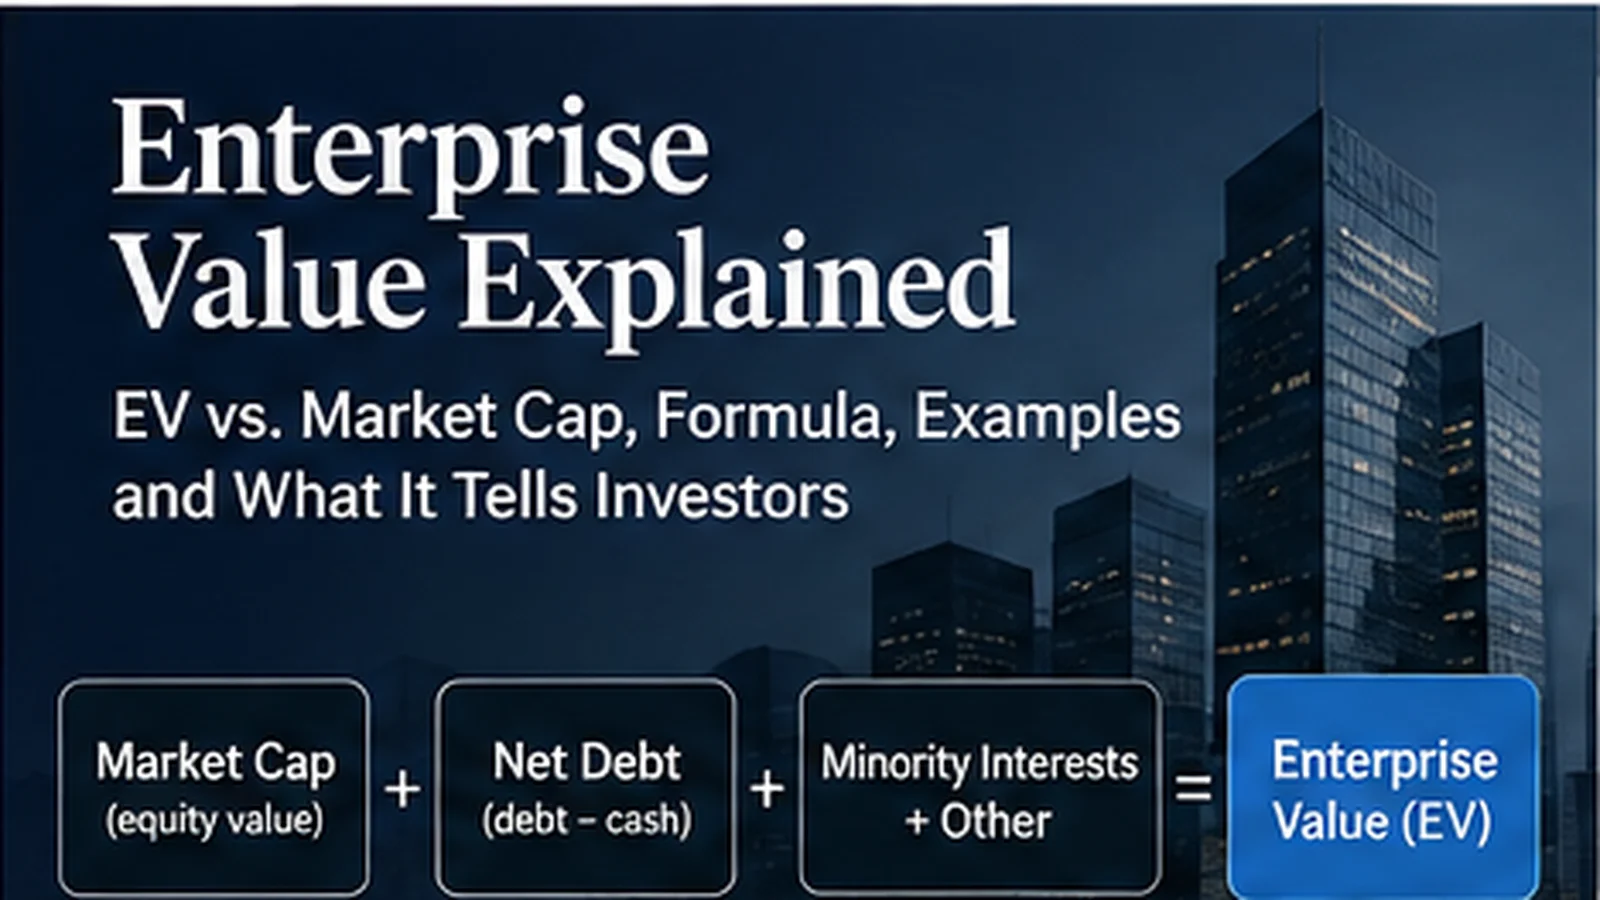
Enterprise value, usually abbreviated EV, is an estimate of the total market value of a company’s core operating business. The simplified formula is:
Enterprise Value = Market Capitalization + Total Debt − Cash and Cash Equivalents.
A more complete version may also add preferred stock, minority interests, unfunded pension liabilities or lease liabilities and may subtract non-operating investments or genuinely excess cash.
The reason is conceptual. Someone buying the whole company would not only buy the common equity. The buyer would also inherit or refinance the debt and would gain access to the cash sitting on the balance sheet. Enterprise value tries to capture that whole-business economics.
Illustrative example only: $10 billion market cap + $4 billion debt − $1 billion cash = $13 billion enterprise value.
Enterprise value vs. market cap
Market capitalization answers: What is the stock market value of the common shares?
Enterprise value answers: What is the approximate value of the operating business after accounting for financing claims and cash?
Neither measure is better in every situation. They are used for different purposes.
If you want to know what common shareholders collectively own at today’s price, market cap is the direct number. If you want to compare operating businesses with different capital structures, enterprise value is often more useful.
This is why enterprise value appears in ratios such as EV/EBITDA and EV/Sales. EBITDA and revenue are generated by the business before interest payments to debt holders, so the valuation numerator should also represent the business before value is split between debt and equity.
Our EV/EBITDA Explained guide goes deeper into that matching principle.
A worked example: two identical market caps, two very different businesses
Imagine two companies, Alpha and Beta. Each has a market capitalization of $10 billion.
Alpha has $1 billion of debt and $3 billion of cash.
Beta has $6 billion of debt and $1 billion of cash.
Alpha’s simplified enterprise value is:
$10B + $1B − $3B = $8B.
Beta’s enterprise value is:
$10B + $6B − $1B = $15B.
The stock market values the two equity stakes equally. The operating businesses are not valued equally. Beta has far more debt sitting ahead of common shareholders, while Alpha has excess cash reducing the effective price placed on its operations.
This is exactly why market cap alone can be misleading when comparing companies.
Why debt gets added to enterprise value
Debt is added because lenders have a claim on the enterprise. If the company changes hands, the debt does not disappear. The buyer either assumes it, refinances it or repays it.
For investors, this highlights a broader principle: leverage can make an equity stake look cheaper than the underlying business actually is.
A company with a $5 billion market cap and $8 billion of debt is not a $5 billion operating asset. The equity is the residual layer after the debt claim.
This is also why two stocks with similar P/E ratios can have very different risk. One may have no debt. The other may be dependent on refinancing markets. An equity multiple alone does not show that difference.
Why cash gets subtracted
Cash reduces enterprise value because the buyer receives it. If you pay $10 billion for the shares of a business holding $3 billion of genuinely excess cash, part of the purchase price is effectively recovered through the balance sheet.
But the word excess matters.
A company needs some cash to operate. Retailers need liquidity for inventory cycles. Industrial companies need working capital. Banks need regulatory capital. A multinational may hold cash in jurisdictions where moving it creates tax or legal friction.
Subtracting every dollar of reported cash can therefore make enterprise value too low. A better analytical question is: how much cash is truly surplus to normal operating needs?
Net cash can make EV lower than market cap
If a company has more cash than debt, enterprise value can be lower than market capitalization.
Suppose a company has a $20 billion market cap, no debt and $5 billion of excess cash. Simplified EV is $15 billion.
That does not mean shareholders can instantly withdraw all $5 billion. Management may retain it, reinvest it poorly or need part of it operationally. But the balance sheet gives the company strategic flexibility that a leveraged peer does not have.
This is one reason a high market cap does not necessarily imply a highly valued operating business.
Why enterprise value matters in acquisitions
Enterprise value is often described as the “takeover value” of a company. That phrase is useful but imperfect.
A real acquisition price can differ because of control premiums, transaction fees, tax structure, debt refinancing, employee compensation, legal liabilities and expected synergies.
Still, EV gets closer than market cap to the idea of what it costs to acquire the operations.
If an acquirer pays $12 billion for the stock of a company with $4 billion of net debt, the economic commitment is much closer to $16 billion than $12 billion.
Preferred stock and minority interest
The simplified formula works well for basic cases, but real capital structures can be more complicated.
Preferred stock sits above common equity in the capital structure and can deserve inclusion in enterprise value because preferred holders have a claim on the business.
Minority interest, or non-controlling interest, matters when a parent company consolidates 100% of a subsidiary’s revenue and EBITDA while owning less than 100% of that subsidiary.
If the denominator contains 100% of subsidiary EBITDA, the numerator should include the value belonging to outside owners. Otherwise the multiple becomes artificially low.
This is one of the most important rules in valuation: the numerator and denominator must describe the same economic claim.
Should lease liabilities be included?
Lease-heavy businesses create another complication. Retailers, airlines and logistics companies may carry enormous lease obligations that are economically similar to debt.
Whether lease liabilities belong in enterprise value depends partly on how the earnings denominator is calculated. If leases are treated as financing obligations in the numerator, the operating metric should be adjusted consistently.
The worst approach is inconsistency. If one company’s EV includes leases and another’s does not, the difference between the two multiples may be methodological rather than economic.
What about pension deficits?
Large unfunded pension deficits can behave like debt because they represent contractual obligations to employees. In mature industrial companies, pension adjustments can materially change enterprise value.
Again, the purpose is not to make every EV calculation maximally complicated. It is to avoid calling two businesses comparable when one carries significant obligations that the other does not.
Can enterprise value be negative?
Yes. A company can have negative enterprise value when cash and cash-like assets exceed market capitalization plus debt and other relevant claims.
At first glance, this looks like free money. Sometimes it is a sign of extreme undervaluation. More often it is a warning that the market expects the operating business to burn cash or face significant future liabilities.
A cash-rich biotech can trade below net cash because research spending may consume the balance sheet for years. A distressed company can have cash today but large contractual obligations tomorrow.
Negative EV should therefore trigger deeper analysis, not automatic enthusiasm.
Enterprise value and EV/EBITDA
EV/EBITDA is popular because it compares whole-business value with a pre-interest earnings measure. The matching is internally logical: both numerator and denominator sit above the split between debt and equity.
The weakness is that EBITDA ignores capital expenditure. Two companies can trade at the same EV/EBITDA while one needs enormous reinvestment and the other converts most EBITDA into free cash flow.
That is why our Free Cash Flow Yield article is a useful companion. Enterprise multiples describe how the market prices operations; cash-flow analysis tells you how much of those operations becomes spendable cash.
Enterprise value and EV/Sales
EV/Sales is often used for young or low-margin companies because sales remain positive when earnings are negative.
But revenue alone says nothing about profitability. Two companies can trade at 5x EV/Sales while one earns 30% operating margins and the other loses money on every incremental dollar.
EV/Sales is therefore best treated as an intermediate metric when margins are expected to mature later.
Enterprise value and EV/EBIT
EV/EBIT includes depreciation and amortization in the denominator. For businesses where depreciation approximates a real economic cost, EV/EBIT may be more informative than EV/EBITDA.
The gap between EV/EBITDA and EV/EBIT can itself reveal how capital intensive a business is. A very wide gap tells you depreciation is a significant part of the economics.
Enterprise value and DCF valuation
Enterprise value is not just a relative-multiple concept. It also appears in discounted cash-flow models.
If you forecast free cash flow to the firm, or FCFF, you are valuing cash available to both debt and equity providers. Discounting FCFF at WACC produces an estimate of enterprise value.
You then bridge from enterprise value to equity value by subtracting debt and other senior claims and adding excess cash or non-operating assets.
Our DCF Valuation Explained guide walks through that process from cash flow to equity value.
Why banks are different
Enterprise value is usually less useful for banks and insurers because debt is part of the operating model rather than simply a financing layer placed on top of operations.
Deposits are both funding and an input into the product. Regulatory capital matters. Interest income is core revenue.
For financial companies, price-to-book, return on equity, capital ratios and earnings multiples are generally more natural starting points.
Enterprise value can change even when the share price does not
Because EV includes the balance sheet, it can change even when market cap remains flat.
If a company generates $2 billion of cash and retains it, enterprise value falls relative to market cap because the cash subtraction gets larger.
If a company borrows $2 billion and spends the proceeds, enterprise value can rise because the debt claim increases without an offsetting cash balance.
This is important when looking at historical EV multiples. A stock can trade at the same share price while the underlying enterprise multiple improves because the business accumulated cash or reduced debt.
Market cap can be the better number
Enterprise value is not always the superior metric.
If your question is specifically about common shareholders, market cap may be exactly what you need. Dividend yield, P/E and price-to-book are equity-level measures and naturally use equity value.
The key is consistency. Use enterprise value with whole-business operating metrics. Use market cap with per-share or equity-level metrics.
Ten common enterprise-value mistakes
- Subtracting all cash without asking how much the business needs to operate.
- Ignoring lease liabilities in lease-heavy peer groups.
- Using stale debt or cash figures with a current market cap.
- Forgetting minority interests when consolidated earnings include subsidiaries not fully owned.
- Ignoring preferred stock or pension obligations when material.
- Comparing EV/EBITDA across sectors with very different capital intensity.
- Treating negative EV as automatic proof of undervaluation.
- Calling EV the exact takeover price.
- Using enterprise value for banks without considering their different balance-sheet economics.
- Mixing enterprise-level cash flow with an equity-only valuation denominator.
A practical enterprise-value checklist
- Calculate market cap using the appropriate diluted share count.
- Add interest-bearing debt.
- Review preferred stock and minority interests.
- Decide whether leases and pensions are economically material.
- Subtract cash that is genuinely excess to operations.
- Review non-operating investments.
- Match EV with EBITDA, EBIT, sales or FCFF.
- Apply the same methodology to every peer.
Enterprise value vs. intrinsic value
Enterprise value is a market value. It tells you how the market currently prices the operating business.
Intrinsic value is an analytical estimate of what the business may actually be worth based on future economics.
A company can trade at an EV of $50 billion while a DCF estimates the operations are worth $70 billion. The difference is the potential mispricing the analyst is trying to understand.
Do not confuse today’s market EV with a fair-value estimate.
Why enterprise value matters more when rates are high
When financing is cheap, investors can become complacent about debt. When interest rates rise, the difference between a net-cash balance sheet and a heavily leveraged one becomes more economically important.
Enterprise value forces the debt claim into the valuation discussion immediately. It reminds you that common equity is only one layer of the capital structure.
That does not mean every leveraged company is unattractive. Debt can improve returns when cash flows are stable and borrowing costs are sensible. It means valuation must account for who else has a claim on the business.
Bottom line
Enterprise value is useful because it solves a simple but important problem: market capitalization tells you what the equity is worth, not what the operating business is worth.
By adding debt and other senior claims and subtracting excess cash, EV creates a more comparable whole-business value. That makes it especially useful in EV/EBITDA, EV/EBIT, EV/Sales, acquisition analysis and FCFF-based DCF models.
The metric becomes dangerous only when the formula is treated as automatic. Cash may not be fully excess. Lease treatment may differ. Pension obligations may matter. Minority interests can distort consolidated earnings. Banks require a different framework.
The best way to use enterprise value is therefore not to memorize one formula, but to understand the matching principle underneath it: compare the value of the claims on the operating business with the earnings or cash flow generated by that same operating business.
Enterprise value FAQ
Is enterprise value the same as market cap?
No. Market cap values common equity. Enterprise value adjusts that equity value for debt, cash and other relevant capital claims.
Why is debt added to enterprise value?
Because a buyer of the business inherits or must refinance the debt. Debt holders have a claim on the enterprise.
Why is cash subtracted?
Because the buyer receives the cash. Analysts should ideally subtract only cash that is surplus to normal operating needs.
Can enterprise value be lower than market cap?
Yes. Companies with substantial net cash can have EV below their equity market capitalization.
Can enterprise value be negative?
Yes. Negative EV occurs when cash and similar assets exceed market cap plus debt and other claims. It often signals that investors expect future cash burn or liabilities.
Is enterprise value useful for banks?
Usually less so. Banks use debt and deposits as part of operations, so equity-based measures such as price-to-book and return on equity are generally more informative.
Sources
- CFA Institute — Market-Based Valuation: Price and Enterprise Value Multiples.
- NYU Stern / Aswath Damodaran — Valuation Definitions and enterprise-value data.
- U.S. Securities and Exchange Commission — Beginner’s Guide to Financial Statements.
This article is educational analysis and does not constitute individualized investment advice.