Data status: September 8, 2026. Brent crude is back near the psychological $100-a-barrel line, and this time the move is not being driven by a neat supply-and-demand spreadsheet. The latest surge follows renewed attacks on Saudi energy infrastructure, persistent disruption around the Strait of Hormuz and a petroleum market that was already far tighter than headline global production numbers suggest.
Associated Press reported Brent around $98.40 on Tuesday and West Texas Intermediate near $93.88. Reuters described Brent approaching $99 after attacks on Saudi facilities added a fresh geopolitical premium. Diesel prices have also become exceptionally expensive, which matters because diesel sits directly inside freight, construction, agriculture and industrial cost structures.
That is why I think the oil price 2026 story is no longer just an energy-market story. Near-$100 oil is becoming a macro variable again.
The most important question is not whether Brent briefly prints $100. Markets have seen three-digit oil before. The important question is whether high crude and product prices last long enough to alter inflation expectations, central-bank policy and corporate margins at the same time.
The market has rediscovered the geopolitical risk premium
The latest trigger is straightforward. Houthi attacks hit energy facilities in southern Saudi Arabia, including infrastructure around Jazan, while the wider Middle East conflict remains unresolved. Markets immediately priced a higher probability that production, refining or shipping could be disrupted.
But the background is more important than the latest headline.
The U.S. Energy Information Administration estimates that oil and petroleum-liquid flows through the Strait of Hormuz averaged only 4.9 million barrels per day in the second quarter of 2026. That compares with 21.6 million barrels per day in the fourth quarter of 2025, before the conflict severely disrupted the waterway.
This is an extraordinary change in one of the world’s most important energy arteries.
Before the disruption, roughly one-fifth of global petroleum-liquid consumption moved through Hormuz. Alternative pipelines exist, but they cannot replace all of that capacity. EIA estimates the Saudi and UAE pipeline systems that can bypass the strait provide roughly 4.7 million barrels per day of alternative capacity.
That means the global system has redundancy, but not enough redundancy to make a prolonged Hormuz disruption irrelevant.
Why $100 oil matters more in 2026 than a simple price chart suggests
Oil affects the economy through several channels at once.
The first is obvious: consumers pay more for gasoline and heating fuels. The second is less visible: transportation, air freight, shipping, plastics, chemicals, agriculture and industrial production all absorb higher input costs.
The third channel is monetary policy.
Central banks can look through a one-off oil spike if inflation expectations remain anchored. They have a much harder problem when higher fuel costs persist long enough to feed into services, wages, freight contracts and corporate pricing decisions.
Our U.S. CPI August 2026 preview already highlights the uncomfortable starting point: energy inflation is elevated before this latest oil move is fully reflected in consumer prices.
Our PPI preview shows the same issue from the producer side. A renewed oil shock does not need to push every component higher immediately. It only needs to remain expensive long enough to raise the cost base of enough industries.
The most dangerous scenario is not $120 oil tomorrow
Markets often focus on dramatic tail risks: Hormuz closes completely, Brent spikes to $150, global recession follows.
That is possible in an extreme escalation. I do not think it is the only scenario investors should fear.
A more subtle and potentially more persistent problem is Brent spending months in a range around $90–$105.
That range is high enough to keep fuel inflation uncomfortable. It is high enough to support producer price pressure. It is high enough to transfer money from consumers toward energy producers. And it is high enough to prevent central banks from declaring victory over inflation.
At the same time, it may not be high enough to destroy demand quickly enough to solve the problem.
That is the stagflationary middle ground: growth slows, but inflation does not fall fast enough to allow easy monetary policy.
EIA’s old base case has already been challenged by events
In its August Short-Term Energy Outlook, EIA forecast Brent averaging about $85 per barrel in the third quarter. That forecast was completed on August 6.
Since then, the market has received another round of attacks and renewed geopolitical escalation.
This does not mean EIA’s framework was wrong. Forecasts are conditional on assumptions, and oil is uniquely sensitive to political events that cannot be forecast precisely.
The useful lesson is that the market is currently trading the distribution of outcomes, not one base-case forecast.
If disruptions ease and flows normalize, prices can fall quickly because high prices themselves destroy demand and incentivize alternative supply. If attacks continue, the risk premium can remain embedded even when physical barrels are still available.
Diesel may matter more than Brent for the real economy
Crude oil headlines attract attention, but refined products determine much of the actual economic pain.
Diesel powers trucking, heavy equipment, agriculture, mining and parts of industrial transport. When diesel prices rise faster than crude, companies can experience margin pressure even if they hedge crude exposure imperfectly.
This is one reason refinery outages matter so much. A refinery problem does not necessarily remove crude from the world. It can remove the specific products businesses and consumers actually need.
That can create a strange market in which crude is expensive, product cracks are even more expensive and inflation pressure broadens through freight and logistics.
What near-$100 oil means for the Federal Reserve
The Fed does not target oil prices. It targets inflation and employment.
But oil can complicate both.
If energy raises headline inflation while consumers cut discretionary spending, the Fed faces a worse trade-off. Raising rates fights inflation but can deepen the growth slowdown. Cutting rates supports activity but can risk validating inflation expectations.
That is why the September Fed meeting has become more interesting. Our Fed September 2026 preview discusses the policy split already visible inside the committee.
A sustained oil shock makes that split harder to resolve.
What near-$100 oil means for the ECB and Europe
Europe is even more exposed to imported energy prices because the region imports a large share of its fossil fuels.
A higher oil price can weaken real household income and raise corporate costs while the euro’s exchange rate determines how expensive that oil becomes in local currency.
This matters for the ECB September 2026 decision. If inflation remains above target and energy rises again, policymakers have less room to support weak industrial growth.
That is a particularly difficult combination for Germany: energy-intensive industry, soft exports and higher borrowing costs can interact in ways that make a simple “higher oil = higher inflation” framework too shallow.
Which stocks benefit from $100 oil?
Energy producers are the obvious first group.
Integrated oil majors and upstream producers usually benefit when realized crude prices rise faster than costs. Service companies can benefit later if high prices encourage more drilling and capital expenditure.
But even inside energy, the impact varies.
A refiner may benefit from wide product margins even if crude costs are high. A producer with hedges may realize less upside than the spot price suggests. A company with operations in politically unstable regions may face higher security or logistics costs.
The strongest beneficiaries are usually companies with low production costs, strong balance sheets and the ability to return cash without needing heroic assumptions about oil staying above $100 forever.
Which stocks are hurt?
Airlines are among the clearest losers because fuel is a large variable cost and demand can also weaken when consumers feel poorer.
Logistics companies face similar pressure. Chemical producers can suffer because oil and natural-gas liquids are feedstocks. Consumer companies can see margin pressure if packaging and freight rise. Automakers can face a mixed effect: higher gasoline can improve EV demand at the margin, but higher inflation and interest rates hurt vehicle affordability.
High-duration technology stocks can also suffer even though they do not use much oil directly. The transmission comes through bond yields.
If higher energy prices cause investors to expect tighter monetary policy, long-term yields can rise. That lowers the present value of distant cash flows.
This is why an oil shock can hit software stocks despite having almost no direct exposure to crude.
Oil at $100 is also a consumer-tax story
Higher oil prices function like a transfer from energy consumers to producers.
For a household, an extra $30 or $50 per month spent on fuel is money that cannot be spent on restaurants, apparel or electronics.
The effect is regressive because lower-income households spend a larger share of income on necessities and transportation.
At the macro level, this can slow discretionary demand without causing the sort of immediate unemployment spike that would make the slowdown obvious.
Retailers can therefore experience weaker traffic before economists declare a recession.
The China demand question still matters
Geopolitics is driving the current move, but demand is not irrelevant.
China remains one of the world’s largest energy consumers. Strong industrial activity, exports and mobility can absorb barrels that might otherwise rebuild inventories.
Conversely, a sharp slowdown in Chinese growth is one of the strongest forces that could offset Middle East supply risk.
This is why oil remains a two-sided market even near $100. Supply disruption can push prices higher. Demand destruction can arrive later and push them lower just as violently.
Inventories are the bridge between geopolitics and price
Markets do not need production to fall today for prices to rise. If traders believe future supply will be tighter, inventories become more valuable.
EIA estimated significant production shut-ins earlier in the year as Hormuz traffic collapsed. Those disruptions forced the market to draw inventories and reroute barrels over longer distances.
Longer routes also tie up tankers. A barrel that spends more days at sea effectively reduces logistical flexibility even if global production is unchanged.
This is why chokepoints matter so much. Oil is not useful merely because it exists. It must exist in the right place, at the right time, in the right form.
Three scenarios from here
Bearish oil scenario: geopolitical premium fades
Attacks stop, Saudi infrastructure returns to normal, Hormuz traffic improves and demand softens under high prices. Brent falls back toward the $70s–$80s. Inflation pressure eases and long-duration equities receive relief.
Base case: oil remains uncomfortably high
Supply remains available but fragile. Brent trades mostly between $90 and $105, enough to keep fuel inflation and freight costs high without causing immediate global demand destruction. This is the most difficult scenario for central banks because inflation remains sticky while growth weakens.
Bullish oil scenario: another major supply disruption
A sustained outage or renewed closure of a major transit route removes physical barrels faster than demand can adjust. Brent moves materially above $110 and product prices spike. Inflation expectations rise, central banks become more hawkish and risk assets reprice sharply.
What I would watch every day
- Brent front-month and the shape of the futures curve.
- Diesel and gasoline cracks, not only crude.
- Strait of Hormuz tanker traffic.
- Saudi and Gulf refinery outages.
- OPEC+ production decisions.
- U.S. and OECD inventory data.
- Two-year and ten-year Treasury yields.
- Inflation breakevens.
- Airline and transport relative performance.
- Energy-sector earnings revisions.
My view
I do not think investors should obsess over whether Brent prints exactly $100. The round number is psychologically powerful and economically arbitrary.
The real threshold is duration.
A one-day spike is a market event. A three-month period around $100 becomes an inflation event. A six-month period becomes a corporate-margin event. A year becomes a capital-allocation event.
The latest attacks matter because they increase the probability that high oil lasts longer than policymakers and investors hoped.
That is the part of the story I would not ignore.
The risk is not simply that oil becomes more expensive. It is that expensive oil keeps interest rates, freight costs and inflation expectations higher for longer — and forces almost every asset class to reprice around a more hostile macro environment.
Oil price FAQ
Why is oil near $100 in September 2026?
Oil prices have risen because renewed attacks on Saudi energy infrastructure and ongoing Middle East tensions have increased concerns about supply, refining capacity and shipping through key chokepoints such as the Strait of Hormuz.
How much oil normally moves through Hormuz?
EIA data show flows averaged 21.6 million barrels per day in Q4 2025 before falling sharply during the 2026 conflict. In Q2 2026, flows averaged only 4.9 million barrels per day.
Does $100 oil automatically mean recession?
No. The economic effect depends on how long prices remain high, wage and income growth, monetary policy and whether consumers and companies can absorb the higher costs.
Which stocks benefit from higher oil?
Low-cost oil producers and some refiners typically benefit, while airlines, transport, chemicals and other energy-intensive sectors can face margin pressure.
Why can oil hurt tech stocks?
The link often runs through inflation and bond yields. If higher energy prices keep monetary policy tighter, the discount rate applied to long-duration growth stocks rises.
Sources
- Associated Press — markets and oil prices, September 8, 2026
- Associated Press — attacks on Saudi energy infrastructure
- U.S. EIA — August 2026 Short-Term Energy Outlook, global oil markets
- U.S. EIA — world oil chokepoints and 2026 Hormuz flows
- IEA — September 2026 Oil Market Report launch
This article is independent financial analysis for educational purposes and does not constitute investment advice.
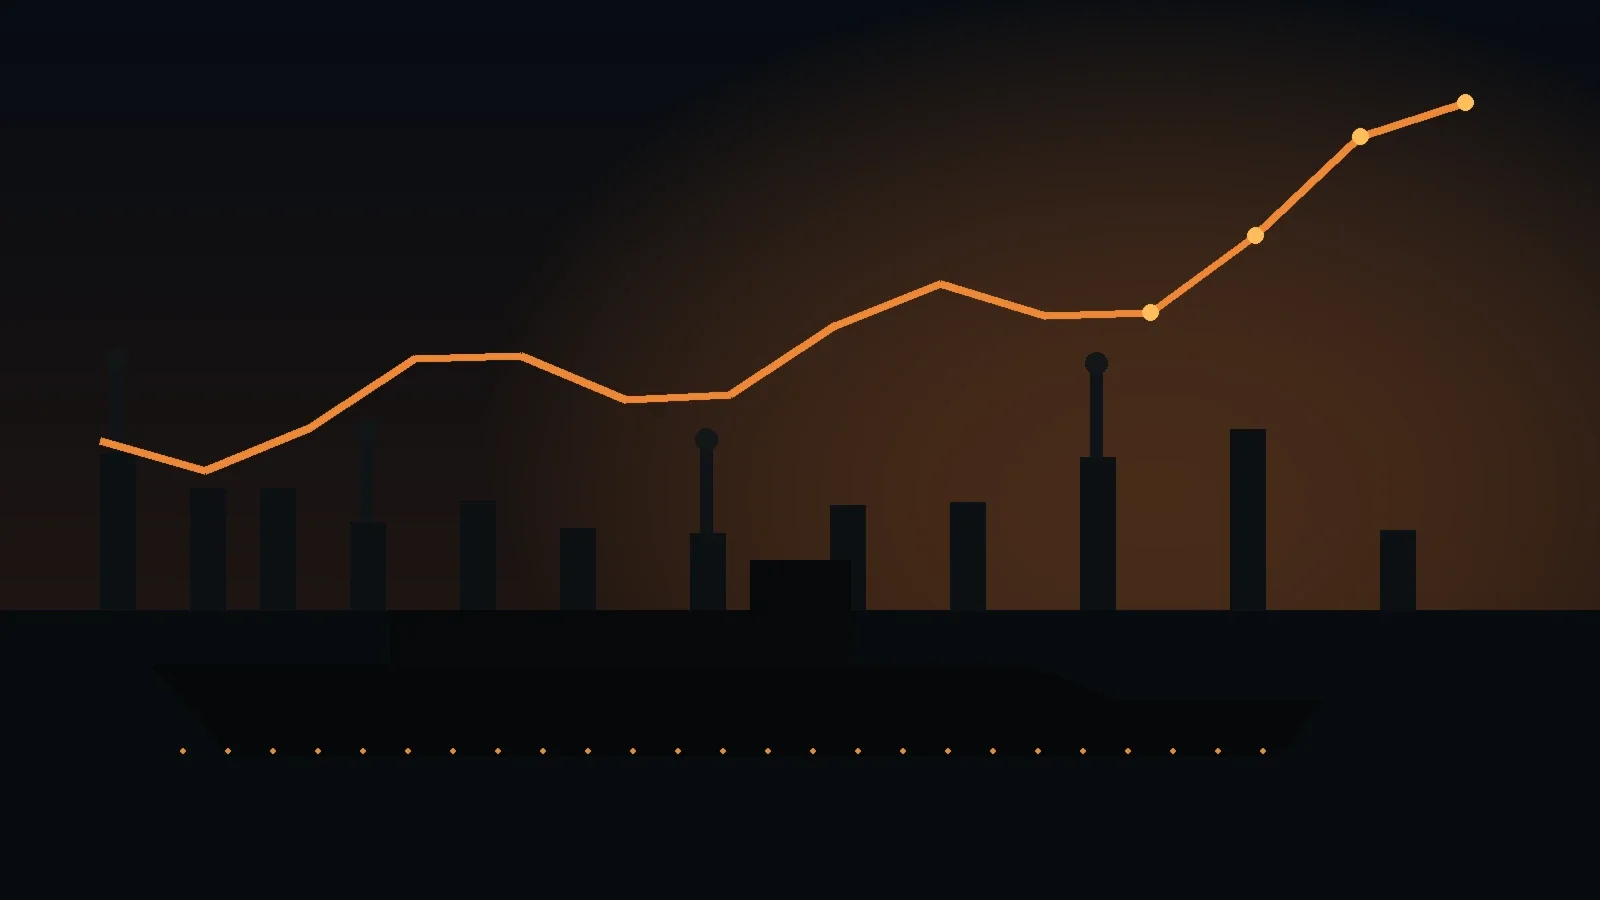
Oil-market stress at a glance
Source: U.S. Energy Information Administration. The chart shows why the current oil shock is fundamentally a logistics and chokepoint problem as well as a production problem.