Data status: September 1, 2026. For years, the easiest criticism of NIO was also the most accurate: the company could sell more cars and still lose more money.
That criticism is becoming harder to make.
In the second quarter of 2026, NIO delivered 107,658 vehicles, up 49.4% year over year. Vehicle sales rose 80.1% to RMB29.06 billion. Total revenue increased 69.1% to RMB32.14 billion. Vehicle margin reached 18.5%, up from 10.3% a year earlier. Gross margin reached 18.4%. Most importantly, adjusted operating profit turned positive at RMB206.9 million.
Yet NIO stock closed August 31 at about $4.23 — effectively at the bottom of its 52-week range — and traded lower again around the earnings release because third-quarter guidance came in below Wall Street expectations.
That tension is what makes NIO interesting now. The operating data look better than they have in years. The stock price says investors still do not trust the durability of the improvement.
The question is no longer simply whether NIO can grow deliveries. It is whether the company has finally crossed the fixed-cost threshold where each additional vehicle creates meaningful shareholder value instead of funding another round of losses.
Q2 2026 is the quarter that changes the debate
NIO reported total revenue of RMB32.14 billion, or roughly $4.74 billion, for the second quarter. That was 69.1% above the prior-year period and 25.9% above Q1.
Vehicle sales increased even faster: 80.1% year over year to RMB29.06 billion. Deliveries rose 49.4% to 107,658 units.
When vehicle revenue grows materially faster than unit deliveries, the implication is usually favorable pricing, mix, or both. In NIO’s case, the launch and ramp of newer premium models such as the all-new ES8, combined with the widening ONVO and Firefly portfolios, is beginning to create a more balanced product mix.
That matters because NIO’s old business model was too narrow. A premium-only strategy made the company aspirational but limited scale. ONVO addresses family-oriented mainstream EV buyers. Firefly moves into smaller premium-compact vehicles. The portfolio now covers more of the Chinese EV demand curve without forcing the core NIO brand to chase low-price segments directly.
The vehicle margin is the number that matters most
NIO’s vehicle margin reached 18.5% in Q2. A year earlier it was 10.3%.
That difference is enormous.
Suppose a company sells RMB29 billion of vehicles. At a 10% vehicle margin, it generates roughly RMB2.9 billion of vehicle gross profit before the rest of the corporate cost base. At 18.5%, the same revenue produces about RMB5.4 billion.
That additional margin can absorb R&D, sales infrastructure, battery-swap investments and corporate overhead. It is the mechanism by which scale becomes profitability.
NIO’s gross profit increased more than threefold year over year to RMB5.91 billion. That is why the quarter feels structurally different from earlier delivery records.
GAAP profitability still has not fully arrived
Investors should not turn one non-GAAP milestone into a victory lap.
NIO still reported an operating loss of RMB347.2 million and a net loss of RMB528.0 million for Q2. Excluding share-based compensation, adjusted net profit was only RMB26.1 million.
That means the company is near breakeven on an adjusted basis, not comfortably profitable on a full accounting basis.
The difference matters because equity compensation is a real cost to shareholders. NIO’s share count has increased materially over time, and StockAnalysis shows approximately 2.50 billion shares outstanding, up more than 14% year over year.
Dilution can quietly absorb operating progress. If the business value rises 20% while the share count rises 15%, per-share value does not rise 20%.
The August delivery update proves that Q2 was not a one-month spike
NIO delivered 35,836 vehicles in August 2026, up 14.5% year over year. Year-to-date deliveries reached 262,893, up 57.9%.
The brand split matters: 21,174 vehicles came from the core NIO brand, 8,810 from ONVO and 5,852 from Firefly.
This is exactly what management hoped the three-brand strategy would accomplish. The premium NIO brand remains the economic anchor. ONVO adds family-oriented scale. Firefly expands the addressable market further downward.
July was even stronger on a growth basis, with 35,934 deliveries, up 71% year over year. The monthly absolute volume is now relatively stable around the mid-30,000 range outside major launch spikes.
The next step is to move toward 40,000-plus sustainably without giving away the margin gains through discounts.
The all-new ES8 is doing disproportionate work
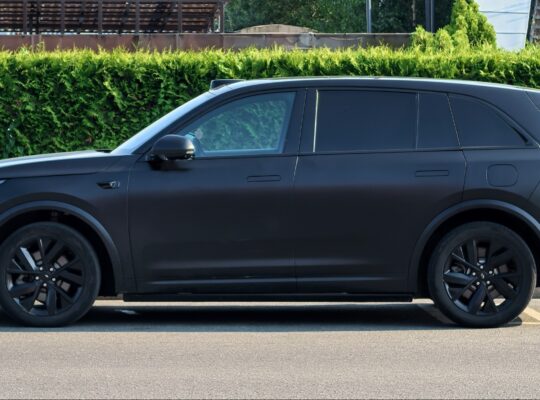
NIO’s all-new ES8 has become one of the clearest examples of what the company can do when product, price and brand all align.
By August 21, cumulative deliveries of the new ES8 reached 140,000 only 335 days after deliveries began. NIO says the model ranked first in cumulative sales from January through July both in China’s large-SUV segment and among vehicles priced above RMB400,000.
That is significant because premium Chinese EV competition has become brutal. Xiaomi is expanding rapidly, Li Auto remains strong in family SUVs, and traditional premium brands are defending share with discounts.
For NIO to hold a leadership position above RMB400,000 demonstrates that the core brand still has pricing credibility even as ONVO and Firefly expand below it.
Battery swap is becoming less of a novelty and more of an infrastructure platform
On August 7, NIO opened its 4,000th battery-swap station and its first fifth-generation station.
For years, investors argued about whether battery swapping was a brilliant moat or an expensive obsession. The honest answer is that it can be both.
The network requires capital and operational complexity. But fixed infrastructure becomes more economically attractive as more brands and more vehicles use it. NIO’s fifth-generation stations are designed for broader compatibility across NIO, ONVO and Firefly models.
This creates the possibility of network-scale economics: the cost of one station is spread across a larger installed vehicle base.
It also changes the customer proposition. Fast charging is improving rapidly across the industry, but battery swap gives NIO a differentiated refueling experience and enables Battery-as-a-Service structures that can reduce upfront vehicle purchase prices.
The hidden risk: infrastructure can become a moat only after utilization rises
A battery-swap station that serves 20 cars a day is a cost center. A station serving hundreds of swaps can become a strategically valuable network asset.
This distinction is why investors should stop counting stations and start thinking about utilization per station.
NIO does not disclose a simple public profitability figure for each station, so external investors cannot precisely calculate the network return. But the direction is clear: the economics improve as fleet size grows without an equal increase in station count.
If NIO needs to build stations at the same rate as vehicle deliveries forever, the fixed-cost leverage will remain weaker than bulls expect.
Q3 guidance explains why the stock did not celebrate
Management guided for Q3 deliveries of approximately 108,000 to 111,000 vehicles and revenue of RMB33.29 billion to RMB34.05 billion.
Those figures imply strong year-over-year growth but only modest sequential improvement from Q2. Wall Street had expected more aggressive revenue progression.
That matters because a stock priced for a turnaround does not merely need “good” growth. It needs evidence that the inflection is accelerating.
The market’s disappointment after earnings is therefore understandable even though the reported quarter itself was strong.
NIO’s $10.6 billion market cap makes the valuation argument unusual
At roughly $4.23 per ADR, NIO’s market capitalization was approximately $10.6 billion at the end of August. Trailing twelve-month revenue was about $14.6 billion.
That means NIO trades below one times trailing revenue.
Revenue multiples are imperfect for automakers because margins matter far more than software-style recurring revenue. But the ratio tells us the market still assigns a very large discount to NIO’s sales base.
Why? Because the company has a history of losses, dilution, capital intensity and competitive risk. The market is effectively saying that revenue scale alone is not enough.
If high-teens vehicle margins and adjusted profitability persist, that discount can narrow. If margins fall back into low teens, the low revenue multiple may be entirely justified.
The balance sheet buys time
NIO ended June with RMB56.7 billion of cash, restricted cash, short-term investments and long-term time deposits — about $8.4 billion.
That liquidity is strategically important. It means the company does not need immediate profitability to survive the next quarter.
But cash is not a reason to ignore burn. A growth company can carry a large cash balance and still destroy value if expansion continually requires new equity.
The correct question is how long the current balance sheet can fund the business while operating cash flow improves.
The three-brand architecture is clever — but dangerous
NIO, ONVO and Firefly give the company access to more customers. They also create complexity.
Each brand needs products, marketing, showrooms or distribution, software support and differentiated positioning. Multi-brand strategies work when shared engineering and infrastructure create more scale benefit than brand fragmentation creates cost.
Volkswagen spent decades learning how difficult this can be. NIO is attempting it while still reaching profitability.
The upside is obvious: one engineering platform can support multiple price segments. The risk is equally obvious: management can spend aggressively to build three brands before any one becomes sufficiently profitable.
The China EV price war remains the existential variable
NIO does not compete in a normal auto market.
China’s EV industry combines rapid innovation with aggressive discounting. BYD uses scale and vertical integration to push prices lower. Xiaomi has enormous consumer-electronics distribution and brand energy. XPeng has improved its product execution. Leapmotor and Geely compete strongly in value segments.
This is why our new BYD analysis matters as a companion piece. BYD’s challenge is preserving margins while globalization offsets weaker domestic sales. NIO’s challenge is reaching profitability before the competitive cycle forces another price reset.
NIO is not BYD — and that can be good or bad
BYD’s scale gives it enormous cost advantages. NIO’s premium positioning gives it a different path.
NIO does not need to outsell BYD. It needs enough volume at high enough gross profit per vehicle to support its technology, battery-swap and service infrastructure.
If the ES8 and future premium models maintain brand pricing while ONVO and Firefly add incremental scale, NIO can build a business with healthier economics than its unit share suggests.
If the entire market commoditizes, premium positioning becomes harder to defend and BYD’s manufacturing scale wins.
The bull case: NIO has already crossed the operating leverage threshold
The strongest bullish interpretation of Q2 is that the difficult investment phase is ending.
Vehicle margins near 18.5%, adjusted operating profit above zero, more than RMB56 billion of liquidity, and a stable mid-30,000 monthly delivery base suggest that fixed costs are finally being absorbed by scale.
If deliveries climb toward 120,000–140,000 per quarter while margins stay in the high teens, full GAAP profitability becomes plausible without requiring heroic assumptions.
At a $10–11 billion market capitalization, even modest future earnings could change the valuation dramatically.
The bear case: Q2 was peak mix, not a new normal
The bearish case is that the margin improvement was unusually favorable.
A strong ES8 mix can lift average selling price. New-product cycles can temporarily reduce discounting. Supplier negotiations can lower costs for a period. But competitors respond.
If NIO has to cut prices to maintain 35,000–40,000 monthly deliveries, vehicle margin can fall quickly. Meanwhile, battery-swap expansion, global distribution and three-brand overhead continue consuming capital.
In that world, Q2 becomes an encouraging quarter rather than a durable earnings model.
Why the stock can double without NIO becoming Tesla
A common mistake is to frame every Chinese EV investment as “the next Tesla.” NIO does not need anything close to Tesla’s historical economics for the stock to rerate.
If the market begins valuing NIO as a credible profitable premium-EV manufacturer rather than a structurally loss-making startup, the change in perceived risk can be large.
But rerating is not the same as guaranteed return. The share count matters. Currency matters. China geopolitical risk matters. And the company still needs to prove cash earnings, not merely adjusted accounting progress.
China-stock risk is not only about the company
International investors demand a discount on many Chinese equities because operating results are only one layer of the risk.
Regulation, ADR structures, U.S.–China relations, capital controls and domestic policy can all change valuation independently of NIO’s car business.
The same discount is visible in technology. Our Alibaba stock analysis shows how even a major AI and cloud business can trade at a persistent country-risk discount.
For investors, that means a “cheap” Chinese stock can remain cheap much longer than a pure earnings model implies.
What I would watch from here
- Vehicle margin: staying above 17–18% would validate the structural improvement.
- GAAP operating profit: adjusted profit is encouraging; full profitability is the next milestone.
- Monthly deliveries: can volume hold above 35,000 and break sustainably above 40,000?
- ONVO contribution: mainstream volume should add operating leverage, not dilute margins excessively.
- Firefly scale: the small-car brand needs to prove it can grow without becoming another costly subscale project.
- Battery-swap utilization: network economics improve only if usage grows faster than infrastructure spending.
- Share count: continued dilution can undermine per-share recovery.
- Cash flow: the ultimate test of whether profitability is real.
My conclusion
NIO’s second quarter is the first in a long time where I think the profitability thesis deserves to be taken seriously.
Revenue growth of 69% is impressive, but revenue was never the real problem. The real problem was that scale did not reach the bottom line. Q2 finally shows evidence that it can.
An 18.5% vehicle margin, 18.4% group gross margin and positive adjusted operating profit represent a very different economic profile from the NIO of 2024 or early 2025.
The stock remains near its 52-week low because investors want more than one quarter. They want proof that margins survive competition, that ONVO and Firefly strengthen rather than dilute the model, and that adjusted profit becomes real cash-generating GAAP profitability.
At roughly $10.6 billion of market value against more than $14 billion of trailing revenue, the valuation leaves room for a major rerating if that proof arrives.
For me, the next phase of NIO stock is not a delivery contest. It is a margin-retention contest. If vehicle margin stays near the high teens while volume expands, the turnaround becomes credible. If margin slips as the company chases growth, the market’s skepticism will have been justified.
Sources
- NIO — Q2 2026 financial results
- NIO — August 2026 delivery update
- NIO — July 2026 delivery update
- StockAnalysis — NIO market data
- StockAnalysis — NIO valuation and share statistics
This article is independent research and not investment advice.
One hidden Q2 asset: NIO’s Shenji chip subsidiary now has an external valuation
NIO’s Q2 release included a detail that is easy to miss beside the margin improvement. Its Shenji chip subsidiary completed two financing rounds in June and August in which outside investors agreed to invest an aggregate RMB493 million at a stated post-money valuation of RMB12.25 billion. After the transactions, a NIO subsidiary is expected to retain a controlling 59.95% stake.
On that headline valuation, the retained stake would correspond to roughly RMB7.3 billion of implied value before considering holding-company discounts, future dilution or any restrictions. I would not add that number mechanically to NIO’s market cap. The more useful conclusion is that external capital is now assigning a real value to an internal technology asset that previously sat mostly inside the R&D expense line.
The financing also supports the broader operating-leverage thesis. NIO is trying to spread software, chips, battery-swap infrastructure and vehicle platforms across three brands. If outside capital can help finance some of those assets while NIO keeps control, less of the burden needs to fall directly on common shareholders.
NIO stock FAQ: the three questions Google users are most likely to ask now
Is NIO profitable in 2026?
Not yet on a full GAAP basis. Q2 produced positive adjusted operating profit and near-breakeven adjusted net income, but NIO still reported a GAAP net loss. The next milestone is durable GAAP operating profit and positive free cash flow.
Why is NIO stock still cheap despite better results?
The market is discounting the risk that 18.5% vehicle margin proves temporary, that competition forces new price cuts, and that dilution or infrastructure spending absorbs the operating improvement.
What is the most important NIO metric next?
Vehicle margin. If NIO can sustain roughly 17–18% or better while deliveries move above the mid-30,000 monthly range, the profitability thesis becomes much harder to dismiss.
Source: NIO Q2 2026 financial results.